For generations, homeownership has stood as a cornerstone of the American dream and a universally recognized rite of passage into adulthood. Yet, over the last five years, the housing landscape has transformed dramatically. A stagnant market driven by severe supply shortages, stubbornly high mortgage rates, and escalating purchase prices has priced countless aspiring buyers out of the market. Consequently, people are renting at rates higher than anything seen in prior generations. According to data from the National Association of Realtors, the median age of a first-time homebuyer in the United States is projected to reach 40 by 2026, underscoring a profound generational shift in how and when people secure permanent housing.
This widespread shift toward renting has forced economists, sociologists, and psychologists to re-examine an enduring cultural assumption: Does owning a home truly make you happier than renting?
The reality, as contemporary research shows, is far more complicated than conventional wisdom suggests. While homeowners consistently report higher levels of satisfaction with their actual living spaces—a contentment that tends to endure for years—translating that comfort into overall life satisfaction is another matter entirely.
Are Homeowners Happier?
When researchers examine the psychological toll and reward of housing tenure, they often find a distinct split between how people feel about their physical homes versus their broader lives.
Long-term research highlights this nuance. A study conducted in Germany tracking individuals over time found that people who moved into a home they owned experienced a lasting surge in housing satisfaction, with little to no fading even after five years. However, that same study revealed that buying a home had no lasting effect on overall life satisfaction.
Much of this discrepancy comes down to financial strain. In a complementary study examining the financial pressures of homeownership, researchers identified the mortgage as the primary culprit. The heavy, ongoing cost of paying off a home loan can lower an individual’s overall life satisfaction enough to completely cancel out the psychological benefits of ownership.
This financial burden is further reflected in cross-national data. A separate study utilizing data from the United States, the United Kingdom, and Australia found that the happiness gap favoring homeowners exists primarily among those who own their homes outright. For homeowners carrying a heavy mortgage and holding little equity, much of that psychological advantage evaporates.
While the financial findings present a mixed picture of happiness, the broader psychological and biological impacts of housing paint an even more striking portrait.
How Owning Impacts Your Psychology
Beyond day-to-day moods, housing stability and ownership appear to leave deep marks on our social lives, mental health, and even our biology.
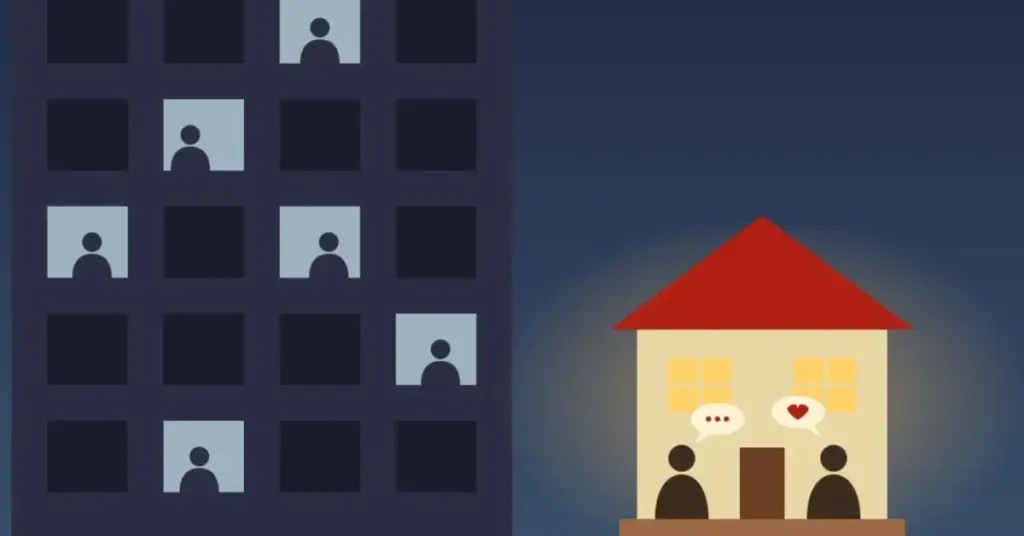
A comprehensive poll of over 10,000 adults in the United Kingdom revealed stark contrasts between renters and outright homeowners. Approximately 40 percent of renters reported feeling lonely, compared to just 29 percent of people who owned their homes without a mortgage. Furthermore, renters were significantly less likely to know their neighbors—43 percent compared to 69 percent among homeowners—and reported lower levels of satisfaction with their friendships, according to data from the Belonging Forum. While researchers note that renters tend to be younger, earn lower incomes, and move more frequently—factors that independently contribute to feelings of isolation—the correlation remains striking.
Perhaps more startling is how housing conditions manifest physically. An observational study involving approximately 1,400 adults in the U.K. found that individuals who rented privately appeared biologically older than homeowners, based on patterns of DNA methylation, a well-established cellular marker of aging. The scale of the effect observed by researchers was unexpected: renting was associated with nearly twice the cellular aging effect of being unemployed versus employed, and roughly 50 percent more than having been a smoker versus never smoking. Because the study was observational, researchers emphasize it cannot definitively prove that renting directly causes faster aging, but the correlation points to the deep physiological toll of housing precarity.
To understand these patterns, researchers point to the chronic stress of instability. A systematic review of 22 studies focusing on renters found that housing insecurity—such as frequent, involuntary moves or the looming threat of eviction—was directly linked to worse mental health in 12 out of 14 studies that examined the variable. Similarly, high rent burdens were linked to declining mental health in six out of nine studies. Ultimately, renting itself may be less damaging than the persistent insecurity and lack of control that frequently accompany it.
The Bottom Line
Homeownership remains associated with tangible psychological benefits, including greater satisfaction with one’s physical environment, tighter community ties, and lower rates of loneliness. When a mortgage is manageable or a home is fully paid off, it clearly supports overall well-being. Furthermore, physical ownership often changes how we relate to our possessions. Research into consumer behavior and access-based consumption, such as car-sharing studies, demonstrates that individuals who share goods rather than own them feel less connected to those items and bear less responsibility for them. Homes may operate under a similar psychological framework.
However, the overarching takeaway from modern research is that much of what makes homeownership feel psychologically rewarding is stability—knowing you can stay put, plant roots in a community, and avoid the anxiety of rising rent next year.
This realization offers encouraging insight for renters. By consciously choosing to stay in one place longer, actively engaging with neighbors, and investing time in the local community, renters can cultivate many of the same psychological benefits historically attributed solely to owning property.
At the same time, the financial mechanics of homeownership cannot be ignored. Even when monthly payments outpace renting, paying off a mortgage functions as a critical forced savings mechanism. Over time, money directed toward a home loan builds equity, eventually transforming into outright ownership of a valuable financial asset.
For younger generations navigating today’s unprecedented economic climate, the traditional calculus of renting versus buying has become extraordinarily complex. But as researchers and housing experts note, external milestones like property ownership are only part of the equation. Ultimately, factors such as pursuing meaningful work, maintaining physical health, and cultivating strong social connections with friends and family remain far more powerful determinants of a fulfilling life than the choice of whether to rent or buy.